Prelims: Cash Reserve Ratio (CRR), Statutory Liquidity Ratio (SLR), Net Demand and Time Liabilities (NDTL), RBI Act 1934, Monetary Policy Instruments, Liquidity Management, Basel III Standards, Liquidity Coverage Ratio (LCR) and Net Stable Funding Ratio (NSFR).
Mains: GS Paper III: Indian Economy, Monetary Policy and Inflation Control, Banking Regulation, Liquidity Management, Financial Stability and Monetary Policy Transmission. |
Why in news?
On 9 October 2026, the Reserve Bank of India (RBI) announced an increase in the minimum daily Cash Reserve Ratio (CRR) maintenance requirement from 90% to 99%.
Key Facts
|
Particular
|
Details
|
|
Regulatory authority
|
Reserve Bank of India
|
|
Announcement date
|
9 October 2026
|
|
Effective date
|
16 October 2026
|
|
Previous daily CRR minimum
|
90% of required CRR
|
|
Revised daily CRR minimum
|
99% of required CRR
|
|
Actual CRR rate
|
3% of NDTL-unchanged
|
|
Fortnightly average CRR
|
100% of prescribed requirement
|
|
Legal provision
|
Section 42(1), RBI Act, 1934
|
|
Main objective
|
Tighter day-to-day liquidity management
|
|
Related measure
|
₹25,000 crore OMO sale
|
|
International banking framework
|
Basel III
|
|
Basel standards-setting body
|
Basel Committee on Banking Supervision (BCBS)
|
What is CRR (Cash Reserve Ratio)?
- The percentage of a bank's Net Demand and Time Liabilities that must be maintained as cash balances with the RBI.
- Banks cannot freely use their mandatory CRR balances for lending or investment. RBI does not pay interest on mandatory CRR balances.
- By adjusting CRR requirements, RBI can influence the amount of money available in the banking system.
Eg. Suppose a bank has Net Demand and Time Liabilities of ₹1,000 crore. At a CRR of 3%: Required CRR is 30 crore. The bank must maintain an average CRR balance of ₹30 crore with RBI over the prescribed reporting fortnight.
What exactly has RBI changed?
- RBI has not increased the CRR rate from 3% to 99%. It has increased the minimum proportion of the required CRR that banks must maintain every day.
- Earlier: 90% minimum daily maintenance of prescribed CRR
- From 16 October: 99% minimum daily maintenance of prescribed CRR
- Actual CRR rate: 3% unchanged
Eg. If the required CRR is ₹30 crore:
|
Requirement
|
Earlier
|
New
|
|
Minimum daily CRR balance
|
₹27 crore
|
₹29.70 crore
|
|
Fortnightly average requirement
|
₹30 crore
|
₹30 crore
|
|
Maximum permissible daily shortfall from ₹30 crore
|
₹3 crore
|
₹0.30 crore
|
What is Net Demand and Time Liabilities (NDTL)?
- The liability base used to calculate CRR and certain other statutory banking requirements.
- Demand Liabilities: Deposits or other qualifying liabilities payable on demand, such as current account balances.
- Time Liabilities: Deposits and other qualifying liabilities payable after a specified period, such as fixed deposits.
- Net Liabilities: The applicable liability base after adjustments prescribed by RBI, including relevant interbank liabilities and exemptions.
- CRR is calculated on the prescribed NDTL base, not simply on a bank's total assets or the sum of every deposit without adjustment.
Why has RBI increased daily CRR maintenance?
- Excess Liquidity in the Banking System
- India's banking system experienced substantial surplus liquidity during August and September 2026.
- Excess liquidity can push short-term money-market interest rates below the policy rate and complicate monetary policy transmission.
- Better Control Over Daily Bank Reserves
- Previously, banks could temporarily maintain only 90% of their required CRR and compensate by maintaining higher balances on other days.
- The 99% rule significantly reduces this flexibility. It helps RBI manage short-term liquidity conditions more closely.
- Strengthening Monetary Policy Transmission
- RBI raised the policy repo rate by 25 basis points to 5.50% in October 2026.
- Excess liquidity can weaken the transmission of monetary tightening to overnight market rates.
- Tighter daily reserve requirements, combined with other liquidity operations, can support closer alignment between money-market rates and the policy stance.
- Liquidity Created Through Foreign Currency Inflows
- Foreign Currency Non-Resident Bank deposits, or FCNR (B) deposits, contributed to banking-system liquidity.
- Banks mobilised foreign currency deposits, and subsequent foreign-exchange swap operations helped provide rupee liquidity.
- Government expenditure also contributed to temporary liquidity surpluses.
How will the New Rule affect the Banking System?
- Daily CRR minimum rises to 99%
- Banks have less flexibility to draw down reserve balances
- More disciplined daily liquidity management
- Potentially tighter overnight money-market conditions
Liquidity Management Instruments Used by RBI
- Open Market Operations (OMO)
- Refers to RBI's purchase or sale of government securities in the financial market.
- OMO Purchase: RBI buys government securities and injects liquidity into the banking system.
- OMO Sale: RBI sells government securities and absorbs liquidity from the banking system.
- On 9 October 2026, RBI announced an OMO sale of ₹25,000 crore for 13 October.
- Repo Rate
- The repo rate is the policy interest rate at which RBI provides liquidity to eligible banks against approved securities through repurchase agreements.
- A higher repo rate generally makes borrowing from RBI more expensive and supports tighter monetary conditions. In October 2026, the repo rate was increased to 5.50%.
- Standing Deposit Facility (SDF)
- SDF allows RBI to absorb surplus liquidity from eligible banks without providing collateral.
- It operates as the floor of the Liquidity Adjustment Facility (LAF) corridor under normal conditions.
- Variable Rate Reverse Repo (VRRR)
- VRRR auctions allow RBI to absorb surplus banking-system liquidity for specified periods at market-determined auction rates.
- They are particularly useful when excess liquidity is temporary.
- Marginal Standing Facility (MSF)
- MSF provides an emergency overnight borrowing facility for eligible banks against permitted securities.
- It normally forms the upper boundary of the LAF interest-rate corridor.
CRR vs SLR
|
Basis
|
CRR
|
SLR
|
|
Full form
|
Cash Reserve Ratio
|
Statutory Liquidity Ratio
|
|
Meaning
|
Mandatory cash reserves
|
Mandatory liquid assets
|
|
Maintained with
|
RBI
|
By banks themselves
|
|
Form
|
Cash balances
|
Cash, gold and approved securities
|
|
Legal basis
|
RBI Act, 1934, Section 42 for scheduled banks
|
Banking Regulation Act, 1949, Section 24
|
|
Primary purpose
|
Monetary and reserve management
|
Liquidity and prudential resilience
|
|
Interest earnings
|
No interest on mandatory CRR
|
Eligible securities may earn returns
|
Basel Standards and Their Relationship with CRR
- The Basel framework is developed by the Basel Committee on Banking Supervision (BCBS), based in Basel, Switzerland, and supported by the Bank for International Settlements (BIS).
- Its objective is to improve banking stability through stronger capital, liquidity and risk-management requirements.
Evolution of Basel Standards
|
Framework
|
Year
|
Major Focus
|
|
Basel I
|
1988
|
Minimum capital requirements for credit risk
|
|
Basel II
|
2004
|
Three-pillar supervisory framework
|
|
Basel III
|
From 2010
|
Stronger capital, leverage and liquidity requirements
|
Basel III: Three Major Pillars
- Pillar 1 (Minimum Capital Requirements): Banks must maintain regulatory capital against credit, market and operational risks.
- Pillar 2 (Supervisory Review): Regulators evaluate banks' risk management, capital adequacy and overall financial resilience.
- Pillar 3 (Market Discipline): Banks disclose financial and risk-related information to promote transparency.
Important Basel III Liquidity Standards
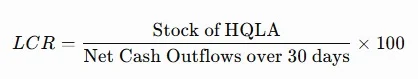
- Liquidity Coverage Ratio (LCR): Ensures that banks hold sufficient High-Quality Liquid Assets (HQLA) to withstand net cash outflows during a 30-day stress scenario.
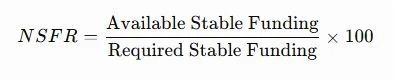
- Net Stable Funding Ratio (NSFR): Ensures that banks maintain stable funding relative to their assets and activities over a one-year horizon.
Difference between CRR, LCR and NSFR
|
Indicator
|
CRR
|
LCR
|
NSFR
|
|
Main purpose
|
Mandatory reserves and monetary control
|
Short-term liquidity resilience
|
Stable long-term funding
|
|
Time horizon
|
Daily and fortnightly compliance
|
30-day stress period
|
One year
|
|
Main requirement
|
Cash balances with RBI
|
High-quality liquid assets
|
Stable sources of funding
|
|
Authority
|
RBI
|
Basel III, implemented by national regulators
|
Basel III, implemented by national regulators
|
|
Relevant figure
|
3% CRR, 99% daily minimum
|
100% minimum
|
100% minimum
|
Impact of RBI's Decision
- Impact on Banks
- Banks will need to manage daily reserve balances more carefully.
- Their flexibility to temporarily use CRR balances for other liquidity needs will decrease.
- Some banks may rely more on interbank borrowing or RBI liquidity facilities to meet short-term funding requirements.
- The actual cost impact will depend on individual banks' liquidity positions.
- Impact on Lending and Borrowers
- The revised rule does not directly increase lending interest rates.
- However, if it contributes to tighter money-market conditions, banks' short-term funding costs could increase.
- The impact on home loans, personal loans, business loans and MSME credit will depend on broader monetary conditions and banks' pricing decisions.
- Impact on Inflation
- Tighter liquidity conditions can support RBI's efforts to control inflation by influencing credit conditions and short-term interest rates.
- However, the daily CRR maintenance change alone is unlikely to produce a large, immediate reduction in inflation.
- Impact on Financial Markets
- Money Market: Overnight interest rates may face upward pressure if surplus liquidity declines.
- Bond Market: OMO sales can increase the supply of government securities in the market, potentially putting upward pressure on bond yields.
- Banking Sector: Banks may need more active treasury and liquidity management.
- Exchange Rate: Liquidity tightening can influence rupee funding conditions, although exchange rates depend on several domestic and international factors.
Significance
- Monetary Policy Effectiveness: Helps RBI maintain better control over short-term banking liquidity.
- Financial Discipline: Encourages banks to maintain reserve balances closer to the prescribed requirement each day.
- Liquidity Stability: Reduces excessive daily fluctuations in banks' use of mandatory reserves.
- Policy Coordination: Complements repo-rate decisions, OMO sales and other liquidity management operations.
- Financial Stability: Supports more predictable reserve management without changing the overall CRR rate.
Challenges
- Reduced Flexibility: Banks have less freedom to manage temporary daily liquidity shortages.
- Funding Costs: Banks with tighter liquidity positions may face higher short-term borrowing costs.
- Uneven Impact: Smaller or less liquid banks may experience greater adjustment pressures than banks holding substantial excess reserves.
- Credit Transmission: Excessive liquidity tightening could affect credit conditions if combined with other restrictive measures.
- Market Volatility: Rapid changes in liquidity conditions may influence overnight interest rates and bond yields.
Prelims MCQ
Q. With reference to RBI's October 2026 decision on Cash Reserve Ratio (CRR), consider the following statements:
- RBI increased the minimum daily CRR maintenance requirement from 90% to 99%.
- The prescribed CRR rate was increased from 3% to 99%.
- The revised requirement will become effective from 16 October 2026.
Which of the statements given above are correct?
(a) 1 and 2 only
(b) 2 and 3 only
(c) 1 and 3 only
(d) 1, 2 and 3
Mains Practice Question
Q. Examine the role of CRR and other liquidity management instruments in maintaining monetary stability in India.
|
FAQs
What is the new daily CRR requirement?
99%, increased from 90%.
When will the new rule take effect?
16 October 2026.
What is the current CRR rate?
3% of NDTL.
Why did RBI increase daily CRR maintenance?
To improve liquidity management.
What is the legal basis of CRR?
Section 42 of the RBI Act, 1934, for scheduled banks.
|

 Contact Us
 New Batch : 9555124124/ 7428085757
 Tech Support : 9555124124/ 7428085757
